icnlive

WATCH LIVE. THINK BUSINESS.

© 2026 ICN.LIVE

ICN.live

PUBLISHED BY ICN PRESS

  • Real GDP rose 7.8 percent in the April to June quarter, above the 7 percent the Reserve Bank of India had projected.
  • Financial, real estate, IT and professional services led the gain, growing 12.1 percent.
  • Investment strengthened, with gross fixed capital formation up 11.9 percent from a year earlier.
  • The reading topped a Reuters poll of economists that had expected close to 7.1 percent.

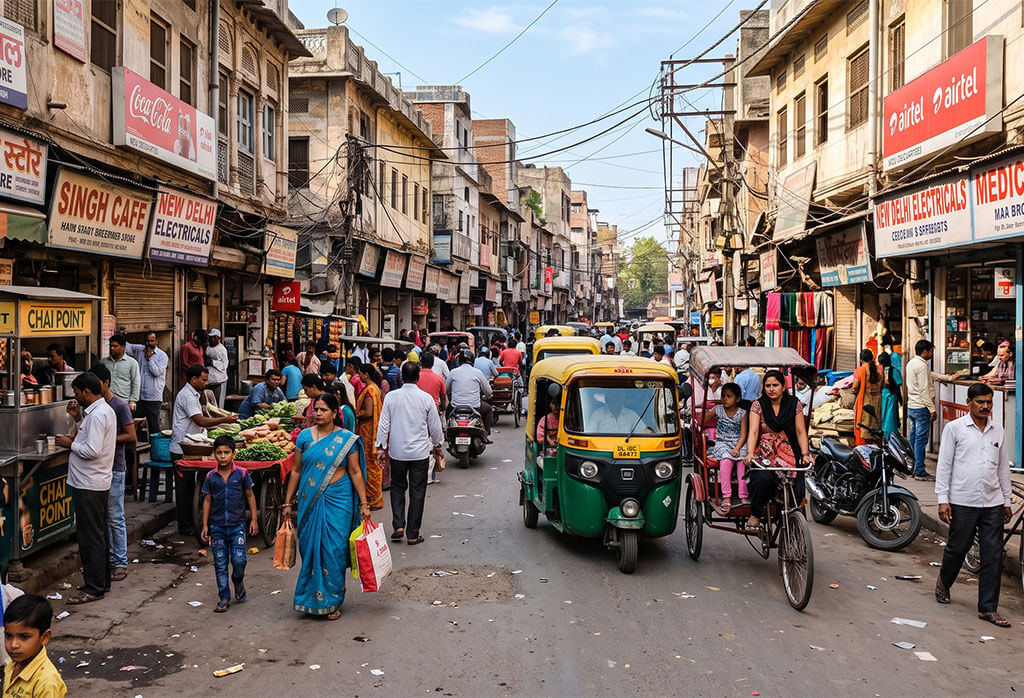
India’s economy beating estimates in the June quarter gave policymakers a firmer read on domestic demand, with real gross domestic product rising 7.8 percent in the first three months of financial year 2026-27. That came in above the 7 percent the Reserve Bank of India had projected, and above a Reuters poll of economists pointing to about 7.1 percent. Growth in the year-earlier quarter stood at 6.9 percent, so the pace quickened from a lower base. Across recent quarters, India’s GDP beating the RBI forecast has become the familiar result, with output landing ahead of the central bank’s own numbers. India’s economy beating estimates has, for now, kept the country among the faster-growing large economies.

What drove India’s economy beating estimates

The tertiary sector did most of the lifting, expanding 10 percent over the year. Within it, the financial, real estate, IT and professional services group grew 12.1 percent. Manufacturing and construction, counted together as the secondary sector, rose 8.6 percent. Agriculture and allied activity grew 3.6 percent, a softer contribution than the rest.

Investment mattered as much as the sector breakdown. The Indian economy’s 7.8% growth reading rested on a sharp pickup in capital spending, with gross fixed capital formation up 11.9 percent from 5.8 percent a year earlier. Private consumption rose 7.1 percent. The April-June quarter GDP figures put real output at 81.36 lakh crore rupees, against 75.46 lakh crore in the same period a year before. Nominal GDP, which is not adjusted for prices, grew 10.3 percent.

The scale of India’s economy beating estimates in the June quarter came from services and investment together, rather than from farm output.

Global pressure and a slower full year

Barclays India chief economist Aastha Gudwani said the Iran conflict had not dented growth as much as some had feared, and she described consumer demand as holding up well. Her read pointed to steady momentum in manufacturing, services, vehicle sales and lending through the quarter. Energy costs tell a harder story. Inflation has been climbing for much of the year, reaching about 4.45 percent in July on the reading available, and the central bank has kept a close watch on oil and supply chains.

The Reserve Bank of India expects the pace to cool over the full year, projecting 6.7 percent growth for financial year 2026-27. It held its policy rate steady at the August meeting rather than raising it, even as several Asian central banks moved. Weather is another risk. El Niño conditions could disturb the south-west monsoon, which would weigh on farm output and rural spending.

Why the number travels beyond India

India’s economy beating estimates does not remove the risks the central bank has flagged, and the full-year path still looks softer than the June quarter. For anyone tracking Indian economy growth in 2026, the quarter shows strength concentrated in services and investment, with agriculture lagging. The India GDP growth Q1 FY27 print also carries weight beyond the country’s borders. MoSPI called the June estimate subject to revision, with the July to September reading due on 30 November. For Gulf economies linked to India through trade, energy and investment, a faster Indian expansion supports export demand and steadies a large partner in an unsettled year.
TAGS

EXPLORE MORE ON:

sovereign USD bond

Qatar has launched a benchmark-sized sovereign USD bond across two tranches, with pricing expected later the same day. The offering is senior unsecured. It comes through the Ministry of Finance, acting for the State of Qatar.

The five-year tranche carries initial price targets of 85 basis points over US Treasuries. Guidance on the 10-year sits at 95 basis points. Both spreads fall below the 100 basis point mark. Final coupons will depend on Treasury levels once the order book closes.

Qatar is the latest Gulf state to return to international debt markets. The move follows a quieter stretch for regional supply during a period of renewed geopolitical tension. Earlier this month, Saudi Arabia raised 3.25 billion dollars through a dual-tranche dollar sukuk.

Business Intelligence & News

  • UAE higher education is becoming core economic infrastructure for talent, innovation, and growth.
  • Abu Dhabi University awarded QS Stars 5+ rating
  • Dubai private university enrolment reached 42,026, growing by around 20% in 2024–25.
  • Universities are aligning skills with AI, finance, healthcare and other strategic UAE sectors.

How the sovereign USD bond is structured

The deal is a Qatar dual-tranche bond, split by maturity. One tranche runs five years. The other runs 10. Each is a senior unsecured bond, which ranks holders alongside other unsecured senior creditors rather than against specific assets.

Initial price thoughts, or IPTs, are the early spread levels shown to investors before the book builds. They mark a starting point, not a final price. As demand forms, the spread can tighten. The US Treasuries spread is the gap between Qatar’s yield and comparable US government debt, and it moves with Treasuries until pricing locks. The sovereign USD bond gives Qatar dollar funding at two points on its curve.

A benchmark-sized transaction points to an issue large enough to trade with reasonable liquidity later. Qatar had not confirmed the final size at launch.

Ratings and syndicate

The State of Qatar holds an Aa2 rating with a stable outlook from Moody’s. S&P rates it AA with a stable outlook. Fitch rates it AA with a negative outlook. The notes are expected to carry a rating in line with the issuer.

Credit Agricole CIB, Deutsche Bank, Mizuho, MUFG, Santander and SMBC serve as joint lead managers. Goldman Sachs International, HSBC, JP Morgan, QNB Capital and Standard Chartered Bank act as joint global coordinators. HSBC is the billing and delivery bank on the five-year tranche. Standard Chartered Bank takes that role on the 10-year.

Settlement and listing

The bonds settle on September 28, 2026. They fall under Qatar’s Global Medium Term Note Programme, the standing framework the sovereign uses for repeat issuance. A listing on the London Stock Exchange Main Market will follow.

Pricing gives a current read on how investors weigh Qatar’s credit. Spreads under 100 basis points on a five- and 10-year sovereign point to steady demand. For the wider Gulf debt markets, the deal adds a fresh reference point after a thin run of supply. Other regional borrowers can price against it.

Qatar’s access to dollar funding rests on large hydrocarbon revenues and a deep pool of state financial assets. That base has long supported its standing with bond investors.

What comes next?

Order books will guide the final spread and coupon on each tranche. Pricing on the sovereign USD bond will firm up once the book closes. Investors will watch the size of Qatar’s prints and where the spreads land against the opening guidance.

Share this post

on your favourite social platforms

or copy the link