icnlive

WATCH LIVE. THINK BUSINESS.

© 2026 ICN.LIVE

ICN.live

PUBLISHED BY ICN PRESS

  • The psychology of money, backed by research on money scripts, shapes results more than salary does.
  • Loss aversion, measured by Kahneman and Tversky in 1979, makes losing feel about twice as painful as winning feels good.
  • Sorting assets vs liabilities and buying back time move money in the right direction.
  • Three books, from Morgan Housel to Daniel Kahneman, map the field for readers who want depth.

The psychology of money decides more about a person’s finances than their salary ever will. Two people can earn the same and land in different places because the beliefs steering their choices differ. Financial psychologists have studied these patterns for decades. Some form in childhood. Others come from fear wired into the brain across thousands of years. The eight principles below pull from that research and from hard practice. Each names a habit that keeps people broke and the shift that turns it around. The last principle points to three books that go deeper than any short summary can. Read to the end for those.

Money scripts run before a person notices them

Every financial choice runs through a script most people never wrote. Researchers sort these subconscious beliefs into four money scripts. The first, money avoidance, treats wealth as something dirty, so a person undercharges and feels guilt about earning. Worship flips that, treating cash as the cure for every problem, so the chase never ends. Status ties self-worth to net worth, which pushes overspending to keep up appearances. Last comes vigilance, steady saving next to steady worry, even with plenty in the bank. Most people carry a blend, with one script leading. Each forms in childhood, often before a kid can define money at all. A child who hears that rich people are greedy stores that line and acts on it decades later. In the psychology of money, spotting the dominant script is step one, because a belief nobody can see keeps steering the wheel without any resistance.

Self-image sets a wealth ceiling

Limiting beliefs about money set a ceiling on income that ability alone cannot break. A person who sees themselves as a $100,000 earner tends to defend that number without meaning to. Earn more, and lifestyle rises to swallow the extra. Fall short, and effort climbs until the familiar level returns. A $200,000 opening slips past anyone still picturing a $50,000 version of themselves. The cap sits in the self-image, not the market.

The psychology of money treats this ceiling as a belief, not a fact. Changing it starts with one honest sentence. Write down the current financial identity, whether that is overspender, chronic saver, or someone scraping by. Beside it, write a truer target, such as a person who builds and manages wealth with ease. Read both before each money decision. As the self-image widens, income tends to move with it. The shift is slow, and it holds.

Assets pay their owner; liabilities charge them

Robert Kiyosaki reduced wealth to one test in Rich Dad Poor Dad. An asset puts money in a pocket. A liability pulls money out. The wealthy stack assets. Middle-class buyers collect liabilities and file them under assets by mistake. A car loses value the moment it leaves the lot, then bills its owner for fuel, insurance, and repairs. Living in a home brings a mortgage, taxes, and upkeep with nothing coming back. A rental property pays every month. Skill courses pay back through higher earnings later. Judging assets vs liabilities before each purchase is where a working money mindset begins. Idle cash carries a quiet cost too. Money parked in a low-rate account loses ground to rising prices year after year. Even savings, left to sit, can slide toward the liability column. The question that reorders spending is short: will this pay back, or drain over time?

A scarcity mindset makes decisions worse

A scarcity mindset does more than sour the mood. When money feels finite, mental bandwidth shrinks and judgment drops. The brain fixes on the next bill and loses the long view. That wiring made sense long ago, when food supplies could run out. Money works differently. It is created every day, and the supply is not fixed. An abundance mindset asks a sharper question. Instead of how to protect what exists, it asks how to create more. That single reframe moves a person from defense to offense. Fear says wait. Possibility says invest. The switch does not come naturally, since humans lean toward caution by default. Training helps. Each time the mind reaches for I cannot afford this, the stronger move is to ask how the thing could be afforded at all. Small reframes, repeated, widen what feels possible.

Every loss can work as tuition

Loss aversion keeps more people poor than bad luck does. Daniel Kahneman and Amos Tversky measured it in 1979, and the finding still holds. Losing $100 hurts about twice as much as gaining $100 feels good. Kahneman later won the 2002 Nobel Prize in economics for the wider work. That imbalance explains a lot of stuck lives. People grip losing stocks and pray for a rebound instead of cutting the loss. Some sit in dead-end jobs because quitting feels like defeat. Others skip raises and dodge investing, since the fear of losing beats the pull of gaining. The cost can be steep.

A person might stay in a draining job two years too long, losing income, energy, and health, all to avoid the feeling of a loss. One fix reframes the setback. A failed venture becomes tuition for a lesson that pays later. Once the loss reads as a receipt for learning, it stops running the show.

Time matters more than money saved

Money multiplies. Time does not. That gap is why saving every dollar can quietly cost a fortune. Consider a worker worth $100 an hour. Two hours spent cleaning to avoid a $50 fee does not save $50. It burns $150, once the lost earning time is counted. Wealthy people run the math the other way. They hire help, buy back hours, and steer that time toward work worth far more. The habit does not require millions to start. Hiring a first assistant early frees a founder to chase revenue instead of chores. The rule scales down as much as up. Someone earning $60,000 a year works out to about $30 an hour, so low-value chores are worth handing off. Anyone can find the number. Divide annual income by roughly 2,000 working hours, and the rate appears. From there, the test is simple. Any task worth less than that rate belongs to someone else.

A new money mindset gets written down first

A money mindset does not change by wishing. It changes on paper, through a small daily act. The method is plain. Write the earliest money memory, then note what parents said and did with cash. That memory usually holds the original script. Once it sits in plain view, a new line can replace it, such as money is a tool for freedom and for helping more people. The same trick works for identity and for spending. List the last ten purchases, then mark each one as an asset or liability with full honesty. Patterns show up fast. Reading these notes before decisions retrains the reflex over weeks, not minutes. The point is not a burst of motivation. Repetition rewires the default, so the calm choice starts to feel normal. Behavior follows the script it is fed, so a better script pays off in time.

The three books worth reading on the psychology of money

Short summaries can point the way, but three books map the whole field. The Psychology of Money by Morgan Housel, published in 2020, sits at the top. It runs on 19 short stories and one core claim: that behavior beats intelligence when it comes to wealth. The book has sold more than 10 million copies worldwide. Thinking, Fast and Slow by Daniel Kahneman comes next. Kahneman, the Nobel laureate behind loss aversion, lays out the two mental systems that drive every money call, one fast and emotional, the other slow and deliberate.

The third pick is Your Money and Your Brain by Jason Zweig, from 2007. Zweig ties neuroscience to investing and shows why the brain chases risk and panics at the wrong moments. None of the three sells a slogan. Each leans on evidence, from Nobel-winning research to market history. Together, they cover the beliefs, the biases, and the brain chemistry behind spending and saving. The psychology of money makes far more sense after reading all three. One honest read can shift the next decision more than any raise.
TAGS

EXPLORE MORE ON:

how to build discipline

How founders build discipline depends on system design, not personal willpower. Many people frame discipline as a fixed trait. They believe a person either has it or does not. The evidence points elsewhere. Discipline usually reflects the environment around a choice. It rarely reflects the character of the person making it. For a founder, that gap matters. A company runs on thousands of small choices made under pressure. The design of a day, a calendar, and a workspace shapes what a founder does next. Small structural choices carry more weight than raw effort.

How Founders Build Discipline Without Relying On Motivation

Willpower is a limited resource. It drains as the day goes on. Strong morning plans often fall apart by evening. A founder who runs on motivation loses focus once fatigue sets in. Structure works another way. A system holds a decision in place no matter the mood or the hour. This idea sits at the core of disciplined entrepreneurship. A repeatable process replaces the daily argument with oneself. The founders who last are not more motivated than their peers. They have removed the moments where motivation gets tested. Motivation feels reliable in the moment. It is not. A plan written on a calm morning survives a hard afternoon far better than a promise made under stress.

Cutting The Decision Fatigue Founders Face Every Day

Decision fatigue means the drop in judgment after many choices. The decision fatigue founders face builds fast. Each open question pulls attention from the next. One fix is to decide ahead of time. A founder maps annual goals once. Then a weekly review sets the priorities. This turns hundreds of daily debates into plain execution. Strong founder productivity habits often come down to this one move. Deciding early guards the energy a leader needs for real work. The daily habits of successful founders show fewer open choices, not more effort.

Replace Weak Habits, Do Not Ban Them

Business discipline also depends on how a founder treats weak habits. Force rarely works for long. A better method swaps the weak habit for a workable one. Then the founder improves that swap over time. Say a leader checks metrics every hour under stress. One scheduled review can take the place of that pattern. Small, staged trades outlast sudden bans. The goal is not instant perfection. It is steady movement toward a better default. Each swap should feel easy to repeat. If it feels hard to sustain, it will not hold. Founders build lasting change through small wins, not through pressure.

The Case For Boring Systems

Good systems rarely feel thrilling. That is the point. A routine full of novelty is not truly a routine. Some founders chase new tools, methods, and frameworks. They mistake motion for progress. Plain, steady execution compounds in a way flashier work cannot. This is where how founders build discipline shows from the outside. The work looks dull and repetitive. Under it sits a set of choices made once and followed without argument. Over months and years, that structure divides the founders who ship from the ones who stall. In the end, how founders build discipline is a question of design, repeated until it holds.

Oura IPO Arrives

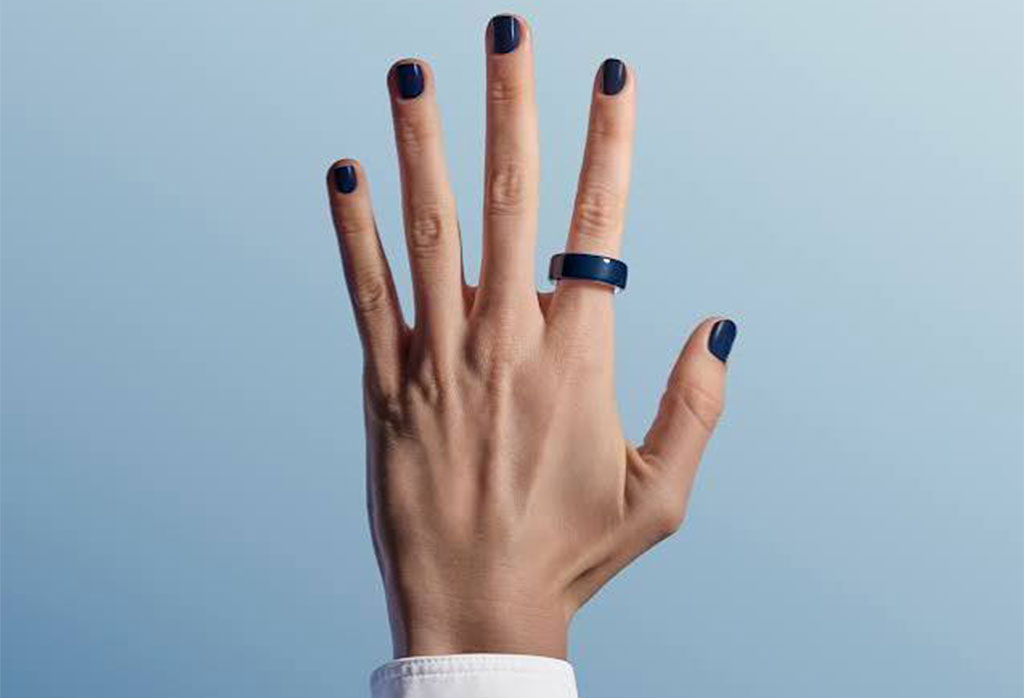
The Oura IPO gives you a clear read on how fast the smart ring market has changed. Oura filed to go public on September 3. The Finnish company built its name on sleep and health tracking, and the numbers show the payoff. Revenue nearly doubled to $1.21 billion for the nine months ending June 30. Oura sold 3.6 million rings over the past year. It now counts around 5 million paid members. The filing follows the launch of the Oura Ring 5, the slimmest and lightest model the company has made.

Early estimates put the offering near $2.5 billion, with a planned listing on Nasdaq. That scale tells you something simple. A product once seen as niche now carries the weight of a public company. The Oura IPO puts that shift in plain numbers.

Why the Oura IPO matters to buyers

Here is what affects you. Competition tends to lower prices and speed up feature releases. More rivals usually means faster upgrades and better value for the ring on your hand. Oura led the smart ring market for years, but rivals are arriving from every direction, each with its own angle. French company Circular says its next ring will let you tap to pay. Chinese company RingConn released a ring this year with haptic vibrations, small buzzes you feel on your finger. That shift changes what a ring can do.

The money behind the challengers

Indian company Ultrahuman raised $70 million this week, with backing from Qualcomm’s venture arm. Ultrahuman wants to build a ring running software on the device itself. Over time, the company says that could power AI features and even games. As a smart ring maker, Ultrahuman is aiming well past sleep scores. Backing from a chip giant like Qualcomm shows the goal is serious.

The Ultrahuman Ring Pro shows the plan in hardware. Priced at $479, it starts shipping in the US in mid-September. It carries a redesigned heart-rate sensor built to read cleaner signals while you sleep. A new dual-core processor, a chip with two cores, handles more accurate data and more work on the device.

The Ring Pro also comes out of a legal fight. Ultrahuman’s US business stalled in October 2025 after the US International Trade Commission ruled for Oura in a patent dispute. The ruling blocked the company from importing new ring inventory. So Ultrahuman rebuilt the Ring Pro with a new form factor to work around Oura’s patent.

Payments, screens, and the race ahead

Circular plans its Ring 3 series for early next year, with a Pro model and a Slim option. Both rings include an NFC chip, the same tap-to-pay tech in your phone, for contactless payments. They also add on-finger vibrations for silent alarms, reminders, and health alerts.

The direction is easy to see. Smart rings were once sold on the idea of stepping away from a screen while keeping tabs on your health. For years, a ring felt lighter than a smartwatch, easy to forget on your finger. That quiet appeal could fade if rings keep adding screens and buttons. Now the race is about how many phone-like features fit inside a two-gram titanium band. Some rings already carry screens, like the Pebble Halo, sold in India for now. Others promise touchpads, like the Dreame Ring. The Oura IPO lands in the middle of this rush.

What Oura Ring alternatives offer now

Shopping for Oura Ring alternatives now means more real choice. Buyers hunting for the best smart rings in 2026 can weigh payments, vibrations, and on-device software against Oura’s tracking. The Oura IPO does not settle the contest. It raises the stakes for every smart ring maker trying to lead. For you, more competition tends to mean more features and better prices ahead.

OpenAI GPT-6 Astra

GPT-6 Astra is OpenAI’s new frontier model, and its arrival brings two questions to the center of the AI market: what these systems can do, and what they cost to run. OpenAI describes Astra as its most capable and most aligned model so far. Access opened first to a limited set of organizations, then widened to paid users across ChatGPT Plus, Pro, Business, and Enterprise. The GPT-6 Astra release date fell in early September, with a limited preview ahead of broader access.

Developers can reach the model through the OpenAI API, Microsoft Azure, and Amazon Bedrock. The company built Astra for long, multi-step work rather than short chat. That design shows in the strongest gains, which sit in GPT-6 Astra computer use. OpenAI says the model can fill out online forms, update customer records, organize a calendar, run research, and draft summaries inside a user’s email or document editor. The aim is a system that finishes tasks, not one that only answers questions.

Business Intelligence & News

  • OpenAI’s advertising revenue reached a $1 billion annualized run rate, the company said.
  • The ad business is about 200 days old and now runs in more than 40 countries.
  • Self-service buying is expanding to India, Europe, the Middle East, and North Africa.
  • The push comes as OpenAI prepares to go public and defends an $852 billion valuation.

What the GPT-6 Astra benchmarks show

The GPT-6 Astra benchmarks published by the company are aggressive. OpenAI says the model saturates FrontierMath Tier 4 at close to 98 percent, reaches 99.9 percent on ARC-AGI-3, and scores 100 percent on ExploitBench. Both the math and reasoning tests were designed to stay ahead of AI systems, so results this high point to a real step up. One caveat matters here. The ARC-AGI-3 score used a general-purpose setup that preserved the model’s reasoning and managed long context, so it is not a clean match with every earlier figure.

Independent testing gives a more measured read. Artificial Analysis found Astra roughly level with its predecessor on overall intelligence, and behind Claude Fable 5.1 on general reasoning, while gaining on coding at lower cost.

On computer-use speed, OpenAI reports a higher score on the OSWorld 2.0 test in about 47 percent less time per task than the prior model, GPT-5.6 Sol. For firms weighing automation of desk work, time per task can weigh as much as raw accuracy.

Cost and cybersecurity set the real test

GPT-6 Astra pricing is where the tradeoff shows most clearly. Standard rates run at 10 dollars per million input tokens and 50 dollars per million output tokens, about 2.5 times the prior flagship’s 4 and 20 dollar rates. OpenAI notes that Astra often uses fewer tokens for similar work, which can offset part of the higher rate. Whether that holds depends on the task. The number worth tracking is cost per finished result, not the headline token price.

On safety, Astra is the first OpenAI model to reach the Critical level for cybersecurity under the company’s internal framework. OpenAI says the model can find unknown security flaws and build ways to exploit them across well-defended systems without a person guiding each step. To limit misuse, the company restricts the most advanced exploit abilities and adds production safeguards. It also flagged a weakness in how well its monitors can read the model’s reasoning under pressure, and named that as open work.

The wider shift is about where value moves. As frontier models take on full tasks rather than single answers, the market question moves from capability alone to capability set against cost and risk. The OpenAI GPT-6 Astra release, arriving alongside strong models from rival labs, brings that calculation into the open for enterprise buyers.

Share this post

on your favourite social platforms

or copy the link