icnlive

WATCH LIVE. THINK BUSINESS.

© 2026 ICN.LIVE

ICN.live

PUBLISHED BY ICN PRESS

  • The UAE’s first retail T-Sukuk subscription runs from June 24 to June 30, 2026.
  • Investors start from a Dh1,000 minimum and earn a 4.30 percent yearly profit.
  • The two-year sukuk lists on Nasdaq Dubai and trades from July 2, 2026.
  • Subscriptions happen online through DFM platforms and five approved receiving banks.

T-Sukuk subscription opened this week, giving UAE residents direct access to a sovereign investment. The UAE Ministry of Finance announced the offering on Tuesday with full pricing details. Citizens and residents can now invest in the country’s first government-backed retail sukuk programme. The total issuance size reaches Dh50 million, equal to roughly 13.61 million US dollars. Your window to subscribe runs from June 24 through June 30 across approved digital channels. Each subscriber buys at face value, paying the full par price during the offering window.

This UAE Retail T-Sukuk carries a two-year tenor and a 4.30 percent yearly profit rate. Officials set the Dh1,000 minimum investment so a wide group of people can take part. Profit payments reach investors every six months until the instrument matures in two years. Each certificate equals one unit, and you can buy more in multiples of Dh1,000. No maximum cap applies, though the government can scale back large requests at its discretion.

Why the T-Sukuk subscription matters now

His Excellency Mohamed bin Hadi Al Hussaini serves as Minister of State for Financial Affairs. He said the opening of subscriptions strengthens the readiness of the UAE’s sovereign investment ecosystem. These channels enable investors to access government products efficiently and transparently, Al Hussaini said. The minister linked the programme to broader plans for public participation in local capital markets. Officials at the Central Bank of the UAE worked with the Ministry on this programme.

For everyday savers, this offering brings a low-risk option backed fully by the UAE Government. The instrument follows Islamic Shariah principles, so it suits people seeking a Shariah-compliant investment. From my standpoint, the Dh1,000 entry point removes a real barrier for first-time investors. Banks and market platforms handle the process online, which keeps participation simple and quick.

How to apply for the T-Sukuk subscription

You first obtain a DFM National Investor Number, known as a NIN, where needed. Approved digital channels include the Dubai Financial Market subscription platform, the DFM app, and iVestor. Emirates NBD Bank acts as the Lead Receiving Bank for this first sovereign issuance. Other receiving banks include Emirates Islamic Bank, Abu Dhabi Islamic Bank, Ajman Bank, and Mashreq Bank. Submit your application through these channels and complete every required step before the window closes. Keep your investor details ready, since accurate identification connects your holdings to the right account.

A completed T-Sukuk subscription places your allocated units into your account before the listing date. Read the official offering documents and check your eligibility before you commit any money.

Nasdaq Dubai listing and secondary trading

Allocation happens right after the subscription period ends, with issuance planned for July 1. The Nasdaq Dubai listing follows, and trading opens to the public from July 2, 2026. You can sell your holdings in the secondary market through brokers licensed on the exchange. Market makers and liquidity providers support trading activity across the listing on an ongoing basis. The Ministry refunds any excess subscription amounts to investors no later than July 7. For markets, this first issuance tests demand for sovereign products among ordinary UAE investors. Officials plan regular issuances, with future tenors reaching up to seven years over time.
TAGS

EXPLORE MORE ON:

Pre-approved home financing in Dubai

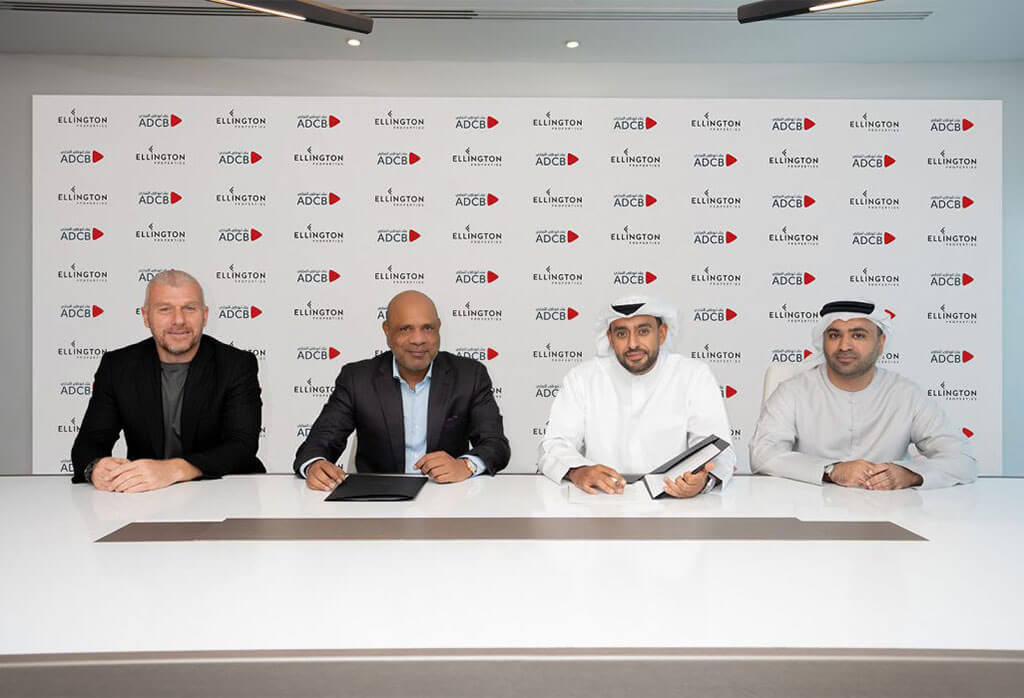
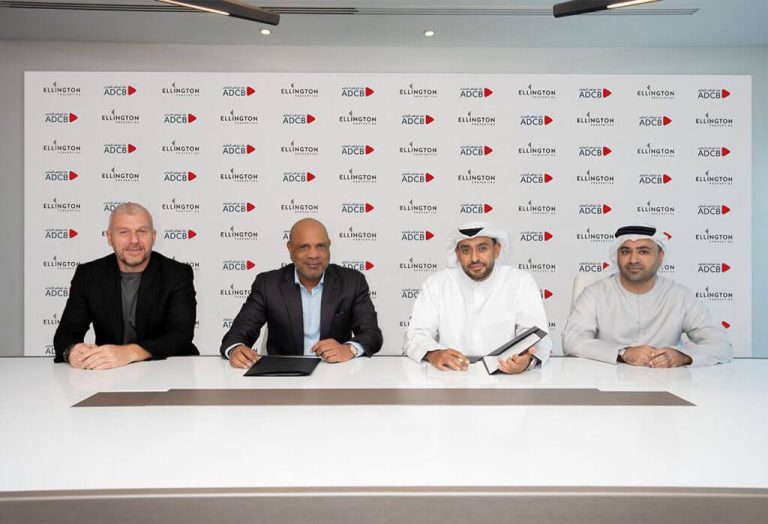
Pre-approved home financing in Dubai picked up a new route this month for anyone eyeing an Ellington Properties home. The boutique developer has partnered with Abu Dhabi Commercial Bank to offer financing that follows a buyer from reservation through handover, whether the unit is still under construction or ready to move into today.

Instead of applying for a mortgage after signing a sales agreement, an eligible buyer secures approval first. That approval travels with them through the milestone payments, construction updates and eventual handover that come with buying property in Dubai. Simple, in theory.

This is not an isolated move. ADCB struck a similar arrangement with Emaar Development in July, bundling mortgage approval directly into that developer’s off-plan sales process. Pairing with Ellington extends the same model to a second major Dubai developer, and signals a bank betting that pre-approved home financing in Dubai will keep pulling buyers toward developments where the paperwork is already half done.

Business Intelligence & News

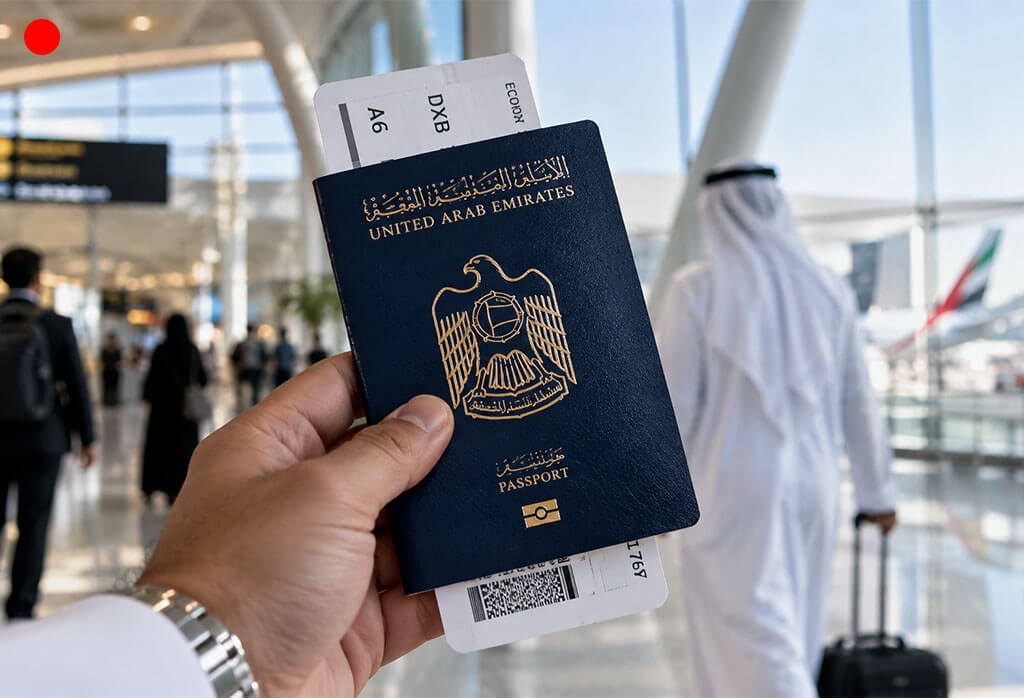
  • UAE passport ranks first globally in 2026, recording a Mobility Score of 182 and worldwide access of 91.9 percent, per Passport Reports’ September ranking.
  • The score covers 128 visa-free destinations, 44 visa-on-arrival or simplified-entry destinations, and 10 reachable through an eTA.
  • Europe, the Gulf, and the Middle East each show 100 percent overall access for UAE passport holders.
  • Only 16 destinations remain visa-required, and the UAE itself ranks 91st out of 199 for inbound travel.

How pre-approved home financing in Dubai works

Under the arrangement, ADCB and Ellington Properties Dubai buyers share a single digital application built for both off-plan and completed units. A dedicated relationship manager stays attached to the file from start to finish. Buyers are not shuffled between departments every time a payment milestone lands.

Off-plan purchases follow a specific structure. Eligible buyers can secure pre-approved financing covering up to 50% of a property’s value. That approval holds for 12 months and renews annually until the keys change hands. Dubai mortgage pre-approval usually means reapplying as construction milestones pass. This structure compresses that into one approval that carries a buyer through, year after year, until the building is complete. Construction timelines can stretch, and a tower meant to top out in 18 months sometimes takes 24. Annual renewal means a buyer’s financing plan does not lapse simply because a project runs long.

What the rates mean for buyers

Rate uncertainty is the usual complaint with early financing offers, since many are pegged to benchmarks that shift with the market. ADCB home loan rates on this program start at 3.49% per annum, fixed for three years. The bank is also waiving processing and valuation fees for a limited time, trimming the upfront cost of getting approved before construction even begins.

Three years of fixed pricing is a meaningful stretch in Dubai real estate financing. Buyers juggling handover payments alongside rent, or an existing mortgage, gain one less variable to plan around. A rate locked at signing does not move if the market tightens later.

A wider shift in Dubai property lending

Developers and banks across Dubai have leaned into bundled financing through 2026, pairing sales offices with in-house mortgage desks rather than leaving buyers to shop separately. The logic is consistent across these tie-ups. Get buyers pre-approved early, then keep them financed through a construction cycle that can run several years.

Ellington Properties, founded in Dubai in 2014, has built its reputation on design-led residential projects across Jumeirah Village Circle, Downtown Dubai and Palm Jumeirah. Linking that portfolio to ADCB’s mortgage arm gives the bank a direct channel into an active off-plan pipeline. It gives Ellington a financing partner its buyers can lean on instead of shopping the open market for a separate lender.

Pre-approved home financing in Dubai used to feel like a separate errand from choosing a unit. Off-plan property financing in Dubai buyers once treated as a background task, now sits inside the same conversation as picking a floor plan. For anyone weighing a reservation on an Ellington unit, the practical move is to ask about pre-approval before signing anything. A rate locked today, at 3.49% for three years, could look considerably better than whatever the market offers by the time a project reaches handover.

Share this post

on your favourite social platforms

or copy the link