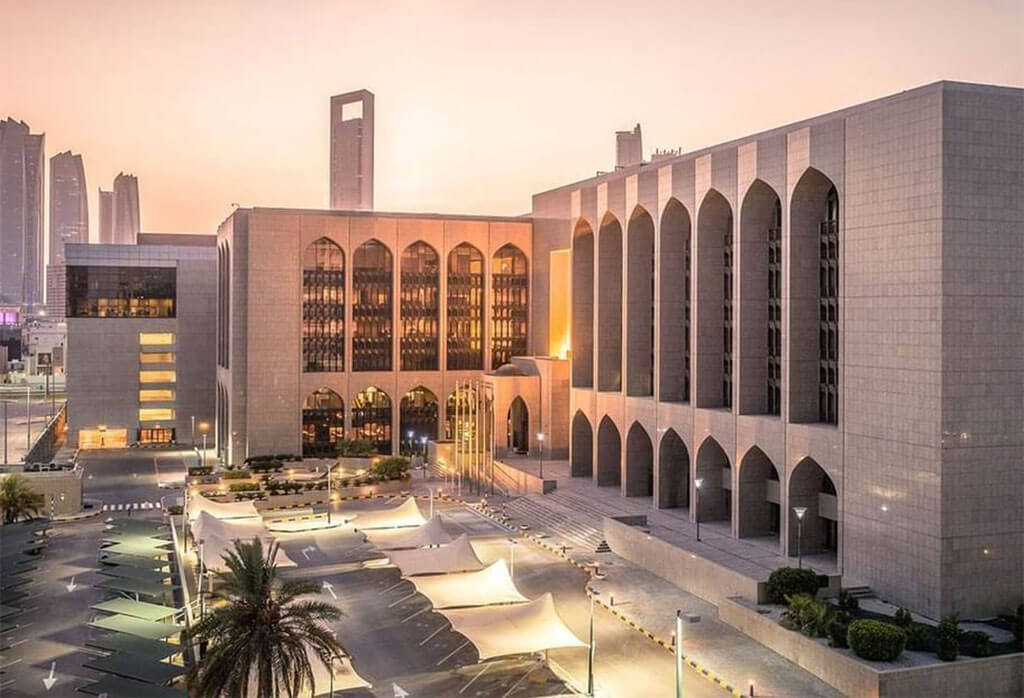

The CBUAE base rate increase takes the UAE base rate to 3.9%, a quarter-point step up from 3.65% that landed on Thursday, September 17. It applies to the Overnight Deposit Facility, the tool the Central Bank uses to set a floor for short-term money in the country. The Central Bank also kept the cost of borrowing short-term liquidity at 50 basis points above the base rate across all standing credit facilities. For most people, the mechanics matter less than the direction. Rates went up. For anyone with a loan or savings account, that direction is what counts.
Why the Fed decides the UAE’s rate
Behind the CBUAE base rate increase sits a US Federal Reserve rate hike of the same size. The Fed lifted its Interest Rate on Reserve Balances by 25 basis points and moved its target range to 3.75% to 4%. Because the dirham-dollar peg fixes the currency at 3.6725 to the dollar, the Central Bank tracks US policy closely to hold that line steady. When Washington moves, Abu Dhabi tends to follow within a day or two. This was the first increase in the UAE rate cycle since 2023, and it reversed a cut made late last year that had taken the rate down to 3.65%. Markets had largely expected the shift, so the reaction at home was calm.
What it means for your home loan
Here is where the numbers reach the kitchen table. Changes in the base rate feed into EIBOR mortgage rates, the Emirates Interbank Offered Rate banks use to price home loans and other credit. If you hold a UAE variable-rate mortgage, your monthly payment could rise the next time your rate is reviewed. A homeowner carrying a large variable loan may pay several thousand dirhams more over a year. Fixed-rate borrowers sit in a calmer spot. Your rate stays put until the fixed term ends, so nothing shifts right away. When that term does end, the loan could be repriced at whatever rate applies then.
Who gains and who pays more
The CBUAE base rate increase does not land on every wallet the same way. Savers may see better returns if banks pass the increase into deposit products, which rewards anyone keeping cash aside. Businesses face the other side of the ledger. Firms carrying variable loans, especially in real estate, construction and SME financing, could see borrowing costs climb while energy and shipping bills already weigh on margins. The effect spreads slowly, through repricing dates and new credit rather than an overnight jump. Households and companies that planned ahead for tighter conditions will feel less of a jolt.
What to watch next
The Central Bank has little room to steer its own course while the peg holds. That keeps attention on the Fed and its next meeting, where policymakers will weigh inflation and jobs data before deciding whether more increases are coming. For UAE residents, the practical questions are close to home. Check whether your mortgage is fixed or variable. Ask your bank when your rate resets. If you are shopping for a loan, factor in that credit costs a little more than it did a week ago. Small steps, but they add up when rates are on the move.