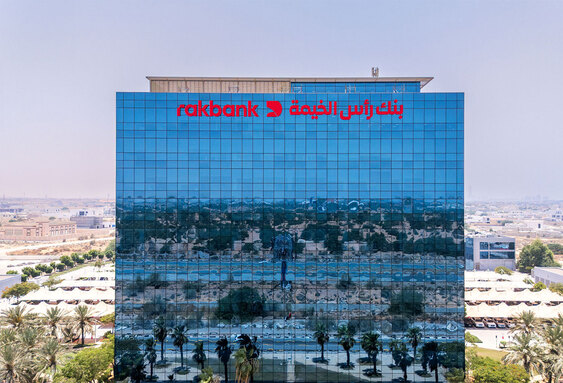
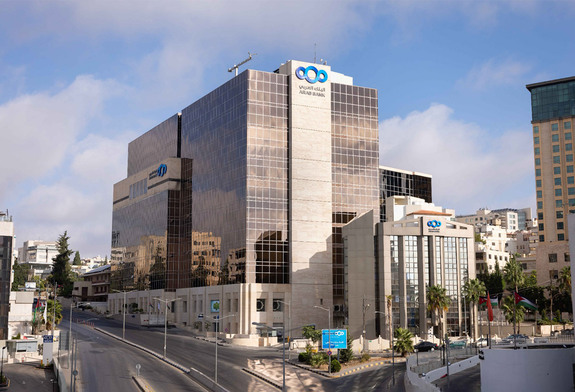

Arab Bank Group’s third-quarter profits confirmed a steady run of growth for one of the region’s largest lenders, with net profit after tax reaching USD 902 million for the first nine months of 2026. The Arab Bank Group net profit figure compares with USD 818 million in the same period a year earlier, an increase of 10%. Growth ran across the Group’s main business lines.
A balance sheet that kept expanding
The Arab Bank Q3 2026 results showed broad growth on the balance sheet. Total assets rose 5% to USD 81 billion, helped by stronger lending and a wider customer base. The loan portfolio grew 4% to USD 42.5 billion. Customer deposits increased 6% to USD 59.3 billion. That mix points to a bank funding its lending through deposits rather than leaning on wholesale markets. Chairman Sabih Masri said the performance reflected a balanced approach that pairs sustainable growth with careful risk management. He pointed to the Group’s wide geographic presence, varied revenue sources, disciplined risk controls, and its work on digital transformation as the pillars behind the numbers.
What Arab Bank Group’s third-quarter profits say about revenue
The Arab Bank’s nine-month profit owed much to income earned beyond traditional lending. Chief Executive Officer Randa Sadik said non-interest income rose 11%, a sign the Bank’s work to build varied revenue sources is paying off and easing its reliance on interest margins. Masri noted the results came against a backdrop of geopolitical strain in the region and wider economic uncertainty that has weighed on business conditions. Even so, the Group held its ground. Sadik tied the outcome to investment in people and technology, alongside governance practices meant to protect long-term value for shareholders, customers, and the communities the Group serves. She framed the period as proof the Bank can grow across all its lines at once.
Capital strength and asset quality
The Arab Bank capital adequacy ratio reached 17.4% under Basel III guidelines, above the minimum the Central Bank of Jordan requires. Sadik said the Bank kept non-performing loan ratios stable and held provision coverage above 100%, a cushion against future credit losses. Liquidity stayed ample, with a loans-to-deposits ratio of 72%. That level leaves room to lend more and to act on investment opportunities as they appear across the Group’s markets. Arab Bank Group’s third-quarter profits also rested on this firm asset quality. The Arab Bank financial results for 2026 describe a lender with capital, funding, and coverage all sitting above regulatory floors.
Digital and AI at the core
Technology ran through much of the commentary on the quarter. Sadik said the Bank’s digital and AI strategy is moving ahead, with wider use of advanced tools inside core banking operations. The work includes a redesign of the digital customer experience, automation of internal processes, and stronger analytics for risk management. New digital services went live during the period, aimed at adding value for customers. The strength behind Arab Bank Group’s third-quarter profits now feeds that technology agenda, with the Group holding a firm position as it invests in the next stage of growth.