icnlive

WATCH LIVE. THINK BUSINESS.

© 2026 ICN.LIVE

ICN.live

PUBLISHED BY ICN PRESS

  • The Bank of Japan raised its main rate to one percent, a level last seen in 1995.
  • A weak yen and rising energy costs from the Middle East conflict pushed prices higher.
  • Governor Kazuo Ueda missed the meeting because of treatment for an infected liver cyst.
  • Higher rates aim to slow inflation while raising borrowing costs for businesses and the government.

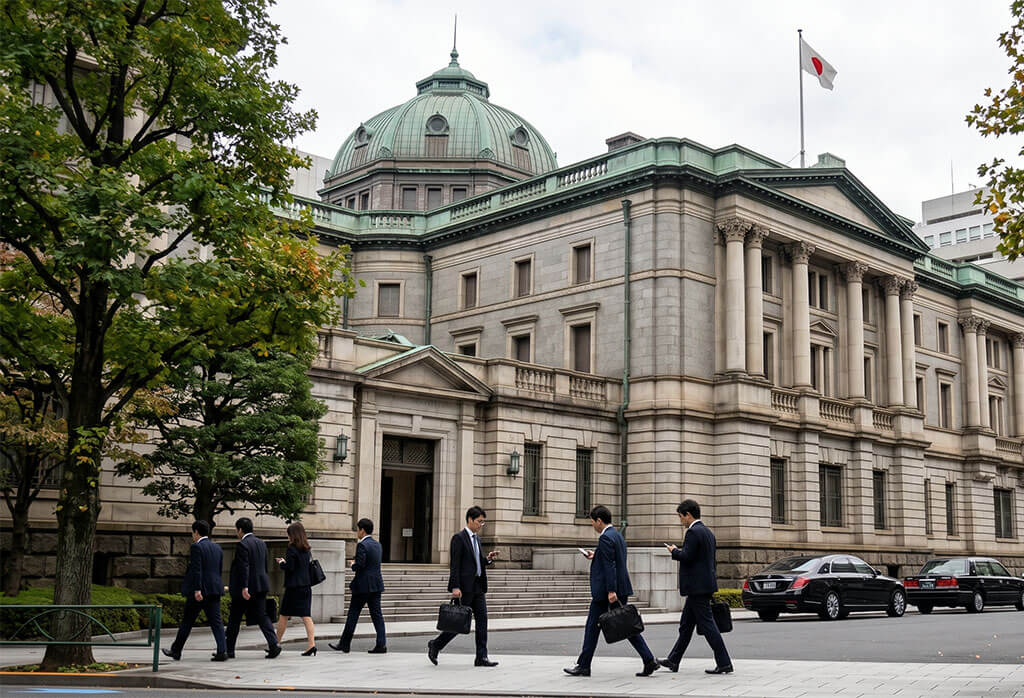
Bank of Japan interest rates climbed to a level not seen since 1995 on Tuesday. The central bank lifted its short-term policy rate to one percent from 0.75 percent. This BOJ rate hike was the first increase since December 2025, when rates reached 0.75 percent. You now watch a Japanese interest rate at a 31-year high reshape borrowing costs across the economy.

Rising energy prices and a weak yen inflation problem forced policymakers to act fast. The conflict in the Middle East drove up oil costs, which hit Japan hard. Japan depends heavily on imported oil and gas, so global price shocks reach consumers quickly. Wholesale prices in May rose over six percent from a year earlier, a three-year peak. Overall inflation reached 1.4 percent in April, still below the central bank’s two percent target.

For you as a reader, these numbers signal a real shift in money policy. Bank of Japan interest rates had stayed near zero for almost two decades before now. Deep rate cuts in the 1990s answered a sharp collapse in property and share prices. Prices fell, and growth stalled, so the economy stayed weak across many of those years.

Why Bank of Japan interest rates matter to you

Higher rates push up the cost of loans for homes, cars, and business spending. The government also pays more interest on its large debt when borrowing costs climb higher. Savers stand to gain because banks start offering better returns on deposits over time. A BOJ policy rate 1% target marks a clear break from years of cheap money. Officials want a normal policy after twenty years of fighting deflation and slow growth.

Governor Kazuo Ueda, Bank of Japan leadership faced a rare test during this meeting. He missed the policy vote while doctors treated him for an infected liver cyst. Eight board members made the call, and they backed the increase by a wide margin. Deputy Governor Ryozo Himino said Japan’s real interest rates still remain at extremely low levels. From my standpoint, this signals more increases ahead despite the leadership gap at the top.

What comes next for the yen and prices

The yen stayed weak this year, which raised import costs for fuel and food. A stronger policy stance can lift the currency and ease some price pressure later. Markets reacted calmly because most investors had expected this move from the central bank. Government steps to ease fuel costs lower the risk of a sharp economic downturn. Bank of Japan interest rates still sit low against most major economies around the world. Analysts expect more steps if inflation stays above the two percent goal for long. You should watch each meeting closely because every decision affects loans, savings, and prices. Bank of Japan interest rates now shape the path for households, firms, and global markets.

The road back to normal policy

The bank started lifting rates in March 2024 after seventeen years without a hike. Each step since then has moved Japan away from emergency measures toward steadier ground. Wage growth gives officials more room to keep tightening without harming the wider economy. Firms keep raising pay and passing higher labor costs into the prices you see. A clear plan helps the bank guide markets while it watches the Middle East risk. Your savings, mortgage, and spending plans all feel the weight of these new decisions.
TAGS

EXPLORE MORE ON:

Pre-approved home financing in Dubai

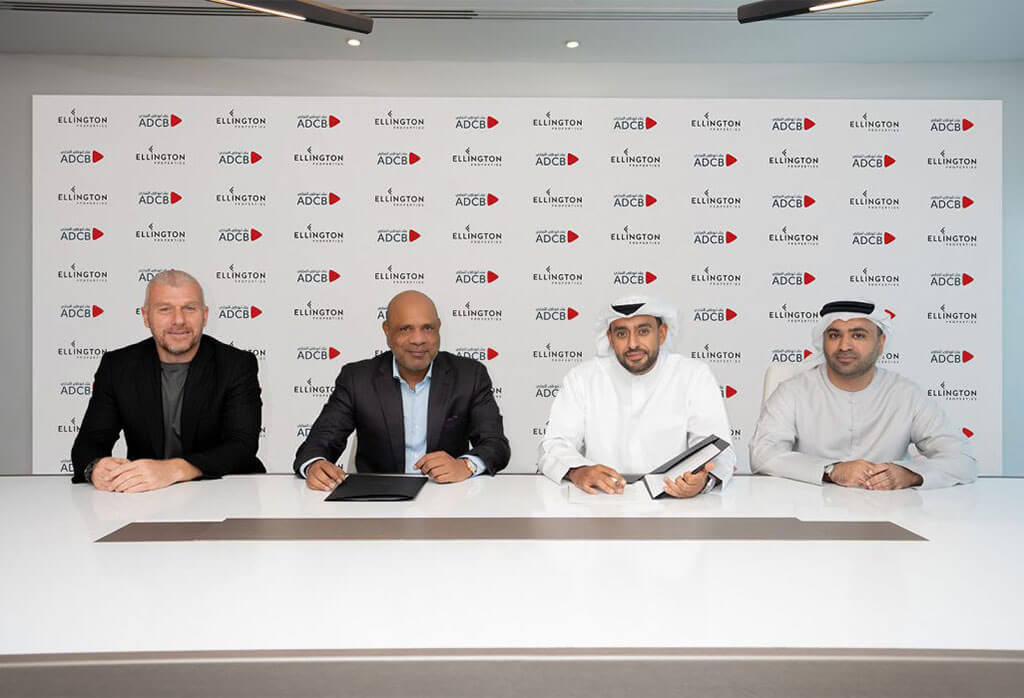
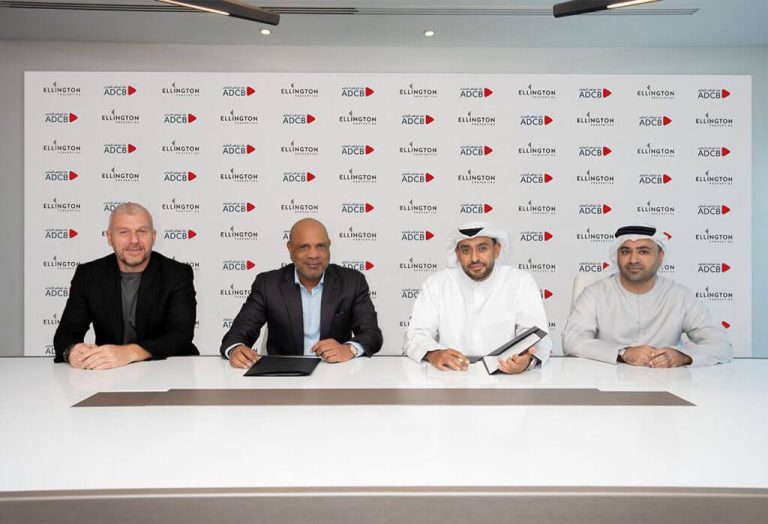
Pre-approved home financing in Dubai picked up a new route this month for anyone eyeing an Ellington Properties home. The boutique developer has partnered with Abu Dhabi Commercial Bank to offer financing that follows a buyer from reservation through handover, whether the unit is still under construction or ready to move into today.

Instead of applying for a mortgage after signing a sales agreement, an eligible buyer secures approval first. That approval travels with them through the milestone payments, construction updates and eventual handover that come with buying property in Dubai. Simple, in theory.

This is not an isolated move. ADCB struck a similar arrangement with Emaar Development in July, bundling mortgage approval directly into that developer’s off-plan sales process. Pairing with Ellington extends the same model to a second major Dubai developer, and signals a bank betting that pre-approved home financing in Dubai will keep pulling buyers toward developments where the paperwork is already half done.

Business Intelligence & News

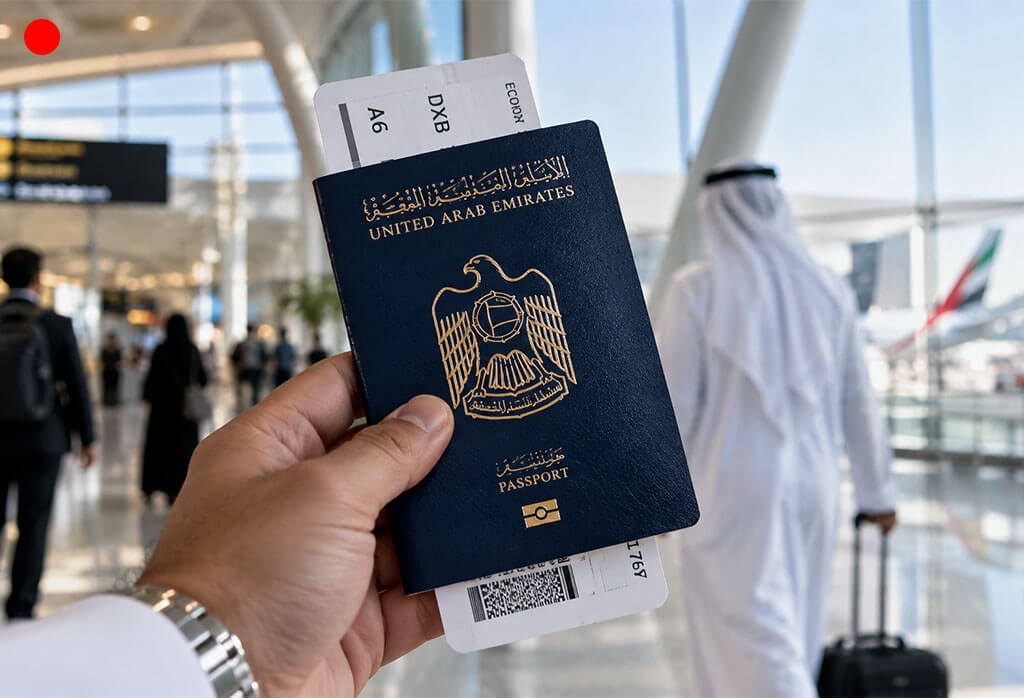
  • UAE passport ranks first globally in 2026, recording a Mobility Score of 182 and worldwide access of 91.9 percent, per Passport Reports’ September ranking.
  • The score covers 128 visa-free destinations, 44 visa-on-arrival or simplified-entry destinations, and 10 reachable through an eTA.
  • Europe, the Gulf, and the Middle East each show 100 percent overall access for UAE passport holders.
  • Only 16 destinations remain visa-required, and the UAE itself ranks 91st out of 199 for inbound travel.

How pre-approved home financing in Dubai works

Under the arrangement, ADCB and Ellington Properties Dubai buyers share a single digital application built for both off-plan and completed units. A dedicated relationship manager stays attached to the file from start to finish. Buyers are not shuffled between departments every time a payment milestone lands.

Off-plan purchases follow a specific structure. Eligible buyers can secure pre-approved financing covering up to 50% of a property’s value. That approval holds for 12 months and renews annually until the keys change hands. Dubai mortgage pre-approval usually means reapplying as construction milestones pass. This structure compresses that into one approval that carries a buyer through, year after year, until the building is complete. Construction timelines can stretch, and a tower meant to top out in 18 months sometimes takes 24. Annual renewal means a buyer’s financing plan does not lapse simply because a project runs long.

What the rates mean for buyers

Rate uncertainty is the usual complaint with early financing offers, since many are pegged to benchmarks that shift with the market. ADCB home loan rates on this program start at 3.49% per annum, fixed for three years. The bank is also waiving processing and valuation fees for a limited time, trimming the upfront cost of getting approved before construction even begins.

Three years of fixed pricing is a meaningful stretch in Dubai real estate financing. Buyers juggling handover payments alongside rent, or an existing mortgage, gain one less variable to plan around. A rate locked at signing does not move if the market tightens later.

A wider shift in Dubai property lending

Developers and banks across Dubai have leaned into bundled financing through 2026, pairing sales offices with in-house mortgage desks rather than leaving buyers to shop separately. The logic is consistent across these tie-ups. Get buyers pre-approved early, then keep them financed through a construction cycle that can run several years.

Ellington Properties, founded in Dubai in 2014, has built its reputation on design-led residential projects across Jumeirah Village Circle, Downtown Dubai and Palm Jumeirah. Linking that portfolio to ADCB’s mortgage arm gives the bank a direct channel into an active off-plan pipeline. It gives Ellington a financing partner its buyers can lean on instead of shopping the open market for a separate lender.

Pre-approved home financing in Dubai used to feel like a separate errand from choosing a unit. Off-plan property financing in Dubai buyers once treated as a background task, now sits inside the same conversation as picking a floor plan. For anyone weighing a reservation on an Ellington unit, the practical move is to ask about pre-approval before signing anything. A rate locked today, at 3.49% for three years, could look considerably better than whatever the market offers by the time a project reaches handover.

Share this post

on your favourite social platforms

or copy the link