icnlive

WATCH LIVE. THINK BUSINESS.

© 2026 ICN.LIVE

Fatima Al-Nouri

Writer,

icn.live

Follow

Fatima Al-Nouri is an experienced journalist passionate about financial freedom. Her career highlights include features on Bitcoin adoption, stablecoins, and global regulation. She received her diploma in Journalism and New Media and continues to engage Arabic-speaking audiences on digital finance.
Lease your iPhone

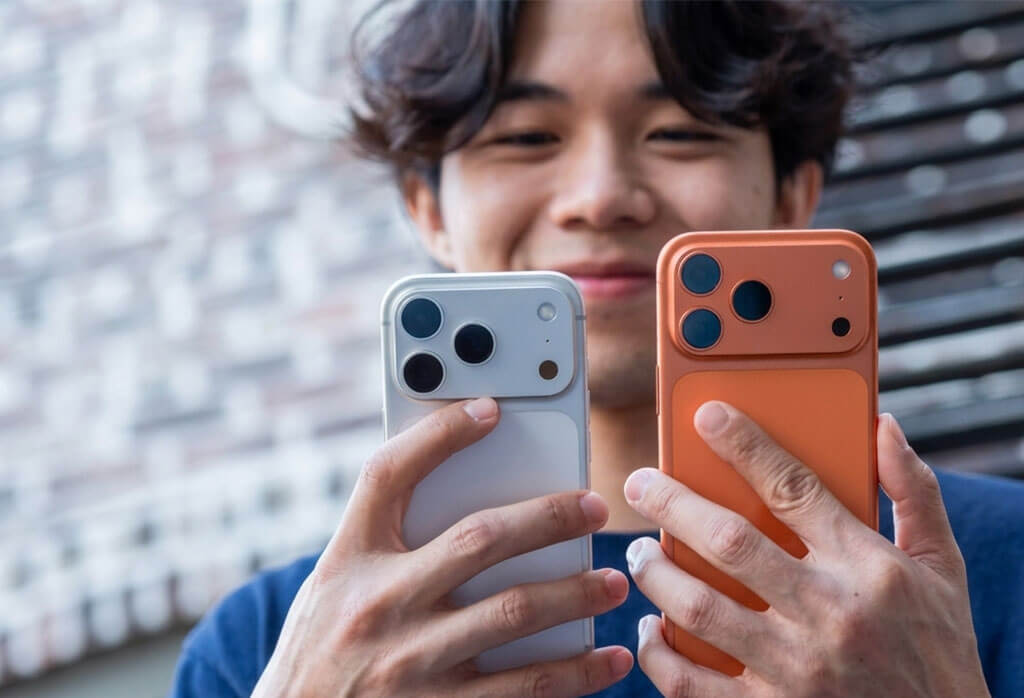
You can now lease your iPhone the way you might rent a car, one steady payment at a time. Apple opened its new leasing program, Apple Upgrade, across the United States on July 28. The service runs through a partnership with Klarna, the buy now, pay later firm. To lease your iPhone, you pass a soft credit check that leaves your score alone. Sign up online, in the Apple Store app, or at a retail store.

What the Apple Upgrade program covers

The plan reaches most of Apple’s current lineup. Think iPhone 17 models, the iPhone Air, newer Apple Watches, Macs, and iPads. iPhones and Apple Watches carry 12- or 24-month terms. Macs and iPads run on 24- or 36-month terms. Cheaper gear sits outside the deal, including the iPhone 16, the base iPad, the Apple Watch SE, and the MacBook Neo. The Apple Klarna partnership handles billing, and you watch every payment inside the Klarna app.

The real iPhone lease cost breakdown. Here is where you read the fine print. When you lease your iPhone, the entry price sounds small at $17.99 a month. A premium model tells a different story. An unlocked iPhone 17 Pro runs $31.99 a month over 24 months, or $45.99 over 12. That 12-month total comes to $551.88, still under the $1,099 shelf price. The iPhone lease cost climbs fast once you pick a high-end phone. Apple says you never pay more than the full list price during a term, taxes and damage fees aside. AppleCare is a separate bill now, so add it to your sum. Trade in an old device and the Apple Upgrade program trims your monthly payment.

How to lease your iPhone and what comes next

Knowing how to lease an iPhone is the easy part. The choice at the finish line matters more. After your term ends, three roads appear. One lets you pay a one-time fee and keep the phone. Another sends it back with nothing owed. The third swaps it for a newer model on a fresh lease. Miss a payment, and Klarna rolls it into the next month with no late fee, though three missed months end the deal. You need to be at least 18 and hold a Klarna account to qualify.

Why Apple built this now

The timing is not an accident. Electronics prices are climbing, pushed by a memory chip shortage Apple has already cited for iPad and Mac price hikes. People hold their phones longer too, with the average American keeping one for 22 months, per a Reviews.org survey. A foldable iPhone is expected in September, and it could be Apple’s priciest handset yet. Leasing moves your focus from a big sticker price to a low monthly figure.

Francisco Jeronimo, an analyst at International Data Corporation, put it plainly. “Apple Upgrade lands at precisely the moment Apple needs it,” he said. My read is simple. The old iPhone Upgrade Program steered you toward a single device. This one wants your whole Apple habit on a subscription. Over four years, leasing a fresh phone every two years can cost hundreds more than buying one outright. Before you lease your iPhone, weigh what always owning the newest model costs you.
Elon Musk's X Money

Elon Musk’s X Money went live in the US in late July, and the headline number is a 6% yield. The rate looks generous. Getting it is another matter. X selects who joins, limits the service to US residents, and sets an age floor of 18. You also need a paid X account before the door opens at all. The catch sits in the fine print. Premium+ subscribers qualify for the 6% APY through their tier. Anyone on Premium reaches the same rate only after a qualifying direct deposit, which means at least $1,000 landing in the account. X calls the rate variable and warns fees can eat into what you earn.

What you actually pay to earn 6%

Run the math, and the shine dulls. X Premium starts at $8 a month, or $84 a year on the annual plan. Premium+ costs $40 a month, or $395 a year. Those fees do not vanish. They come straight out of your interest. Say you pay $8 monthly. Over a year that is $96. A 6% return on $1,600 also comes to $96 before tax. Your yield and your subscription cancel out. On the annual $84 plan, you would need roughly $1,400 sitting in the account to break even. Premium+ raises the bar hard. Its $395 annual fee needs about $6,583 at 6% to cover the cost. Pay monthly, and the total climbs to $480, pushing the break-even balance near $8,000. If you already buy Premium for verification, ads, or Grok, that changes the sum. Someone who signed up only for the yield sees a much smaller net return.

How Elon Musk’s X Money is built

Underneath Elon Musk’s X Money sits a bank partnership. X Payments runs the front end, but it is not a bank. Cross River Bank holds the deposits and provides the regulated banking underneath. X also spreads eligible balances across partner banks through a cash sweep program. That structure lets the published terms advertise up to $10 million in aggregate FDIC coverage. Standard protection stays at $250,000 per depositor, per insured bank, per ownership category. X Payments itself carries no FDIC insurance. The product does more than pay interest. An X Money Visa debit card gives 3% cashback on eligible purchases, with no foreign transaction fees. X refunds ATM charges within three days. Because Visa accepts the card everywhere, you can spend outside the app. Peer-to-peer transfers, bill pay, wires, mailed checks, and early direct deposit round out the account.

Who gets in, and who waits

Elon Musk’s X Money eligibility comes down to three gates. First, an X Premium+ subscription or a qualifying Premium account. Second, an invitation from X. Third, for Premium members, the direct deposit condition. Free accounts get nothing yet. People outside the US stay locked out too. Invitation control lets X manage how many users flood in during the first phase, while Cross River handles deposits, payments, and compliance.

My read on the 6% hook

Here is my read. The 6% is a customer acquisition hook, and a sharp one. It pulls attention and gets people talking about Elon Musk’s X Money as a bank rival. But the number you see is not the number you keep. Premium+ users pay the most for direct access. Those on regular Premium pay less and work for it. Whether X holds this rate once the crowd arrives is the real question, and I would not bet on 6% lasting forever.

Kuwait $6 billion bond sale

The Kuwait $6 billion bond sale closed this week with an order book the finance ministry calls one of the largest for a multi-tranche sovereign deal in 2026. Three tranches went out. Investors took $3 billion in three-year paper, $1.5 billion in five-year notes and $1.5 billion at 10 years. Final spreads landed at 70, 75 and 85 basis points over US Treasuries. It was the country’s first international issuance since October last year.

Pricing tells you more here than the headline number does. Kuwait tightened 25 basis points across all three tranches from its opening levels, according to a person familiar with the deal cited by Bloomberg. Buyers do not give up that much yield to a borrower they distrust.

Demand for the Kuwait $6 billion bond sale came in two versions. The finance ministry put total orders above $18 billion, more than three times the issue size. Bloomberg reported books near $14.8 billion at final terms. Peak interest and final interest are different numbers, and both can be accurate.

Who bought the Kuwait $6 billion bond sale?

American accounts took 48 percent of the allocation. The UK and Europe followed with 28 percent, then the Middle East and North Africa at 16 percent. Asia took 4 percent, and other international markets took the rest. Finance minister Yaqoub Al-Refaei said the result shows investor confidence in Kuwait’s credit position and financial standing.

The short end did the heavy lifting. Half the total sat in the three-year tranche, which points to buyers who want yield without long duration risk. Five- and 10-year paper gives other Kuwaiti borrowers a benchmark to price against.

Geography matters more than usual on this one. JPMorgan reclassified Kuwait as a developed market in February 2025 and removed it from its emerging market bond index. That move stripped out index-driven demand the country once attracted by default. Pulling almost half the book from the Americas without that support is a real result for a Kuwait sovereign bond issuance.

War risk barely moved the price

Iranian attacks have hit US military assets in Kuwait and Bahrain in recent weeks. Fixed income desks priced the three-tranche bond sale anyway. Gulf sovereign bonds already went through this test once, falling to lows in mid-March before climbing back through late April. Traders have a reference point now, and they used it.

Why Kuwait keeps borrowing

The arithmetic is plain. Kuwait’s 2026-27 budget forecasts revenue of KD16.3 billion against spending of KD26.1 billion. That leaves a Kuwait budget deficit of KD9.8 billion, up from KD6.3 billion the year before. Oil was expected to supply close to 80 percent of budgeted revenue, so disruption around Hormuz cuts straight into the top line.

Access came back through legislation. The Kuwait public debt law, approved in March 2025, set the borrowing ceiling at KD30 billion, roughly $97.4 billion, and allowed maturities out to 50 years. Political gridlock had kept the country out of the sovereign market for eight years before that. Since the law passed, Kuwait raised $11.25 billion in October 2025 and another $2 billion in May.

Kuwait is building a yield curve, and curves need repeat business. Each deal hands domestic banks and corporate borrowers a pricing reference they did not have. I read the Kuwait $6 billion bond sale as a curve-building exercise first and a cash-raising one second. The deficit is real. So is the sovereign wealth sitting behind it. What global investors bought this week was the legal framework and the balance sheet, not the news cycle.