icnlive

WATCH LIVE. THINK BUSINESS.

© 2026 ICN.LIVE

ICN.live

PUBLISHED BY ICN PRESS

  • NBQ reported a profit after tax of AED271 million for the six months to 30 June 2026.
  • Customer deposits rose 29 percent to AED17.1 billion, and total assets grew to AED24.1 billion.
  • The capital adequacy ratio held at 31 percent, while the non-performing loans ratio stayed low at 0.4 percent.
  • Net interest income held about flat at AED310 million as interest rates fell.

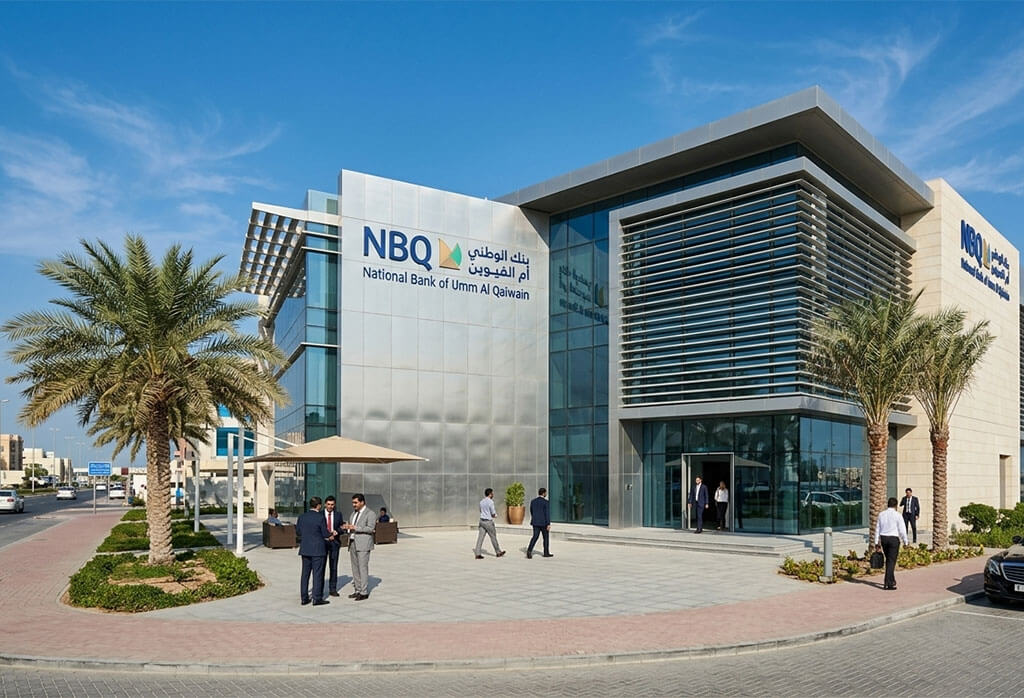
NBQ’s 2026 half-year profit came in at AED271 million for the six months to 30 June. Behind that figure sit the depositors, borrowers and staff who keep the lender running. The National Bank of Umm Al Qaiwain results point to steady footing at a small bank that families and businesses in the northern emirates lean on for everyday needs.

What NBQ’s 2026 half-year profit shows

The bank credited its first-half showing to a wider mix of income and a broader balance sheet, paired with tight cost control. Total interest income reached AED503 million over the period. Net interest income held about flat at AED310 million, against AED309 million a year earlier. That flat line matters more than it looks. Interest rates fell over the year, so keeping core income steady took real work on both pricing and funding.

For a customer, this shows up in small ways. Your deposit stays safe. Loan terms stay predictable. A bank that earns steadily can keep the lights on for the people who bank with it.

Balance sheet growth and deposits

NBQ total assets rose to AED24.1 billion by the end of June, up 5 percent from December and 20 percent from a year earlier. Customer deposits did much of the heavy lifting. They climbed 29 percent to AED17.1 billion, a sign that more people trusted the bank with their money. Net loans and advances grew 4 percent over the year to AED8.7 billion. Shareholders’ equity reached AED6.4 billion, up 3 percent from June 2025.

Deposit growth on that scale tells a human story. When savers move money into a bank, they place a bet on its stability. That trust gives the lender room to fund loans for homes, shops and small firms across the emirate.

Capital strength and asset quality

The capital adequacy ratio stood at 31 percent, well above the floor the Central Bank of the UAE sets under Basel III rules. Put simply, the bank holds a thick cushion against shocks. The non-performing loans ratio came in at 0.4 percent, up slightly from 0.3 percent at the end of 2025 but far below the 2.2 percent seen a year earlier. Fewer bad loans mean fewer customers in distress and a cleaner book. NBQ net profit after tax landed at AED271 million on the back of these numbers.

Adnan Al Awadhi, Chief Executive Officer of NBQ, said the bank delivered solid results despite geopolitical uncertainty and lower interest rates. He pointed to a diversified model, careful balance sheet management and a focus on lasting growth. Al Awadhi said the bank kept strong capital and liquidity while supporting customers and the wider economy through prudent risk management and better asset quality.

He added that NBQ kept investing in digital tools to improve the customer experience and to make its platforms safer and more reliable. Partnerships would widen its services further, he said. Al Awadhi also restated the bank’s pledge to Emiratisation, leadership development, sustainability and community work.

Why NBQ’s 2026 half-year profit matters to customers

Numbers like these can feel far from daily life. Yet a stable bank shapes real choices for real people. NBQ’s 2026 half-year profit gives the lender the means to keep lending, keep hiring and keep serving the towns it calls home. For anyone who banks there, that steadiness is the point.
TAGS

EXPLORE MORE ON:

Pre-approved home financing in Dubai

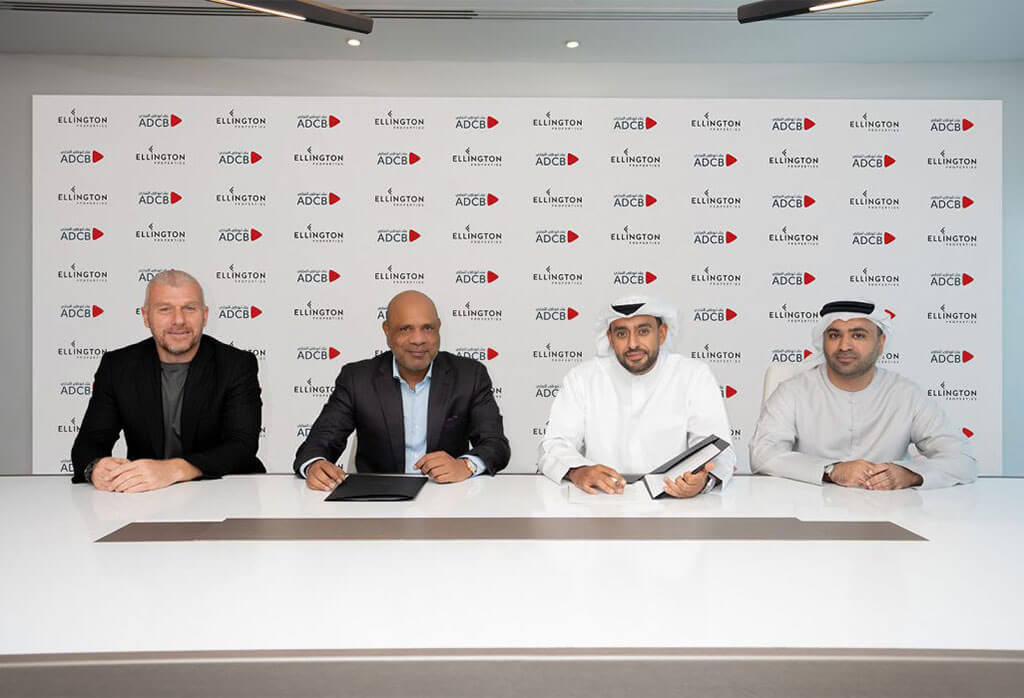
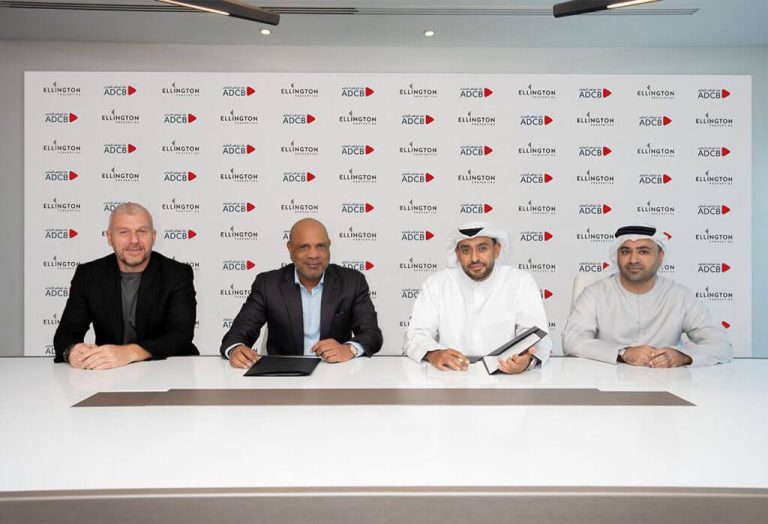
Pre-approved home financing in Dubai picked up a new route this month for anyone eyeing an Ellington Properties home. The boutique developer has partnered with Abu Dhabi Commercial Bank to offer financing that follows a buyer from reservation through handover, whether the unit is still under construction or ready to move into today.

Instead of applying for a mortgage after signing a sales agreement, an eligible buyer secures approval first. That approval travels with them through the milestone payments, construction updates and eventual handover that come with buying property in Dubai. Simple, in theory.

This is not an isolated move. ADCB struck a similar arrangement with Emaar Development in July, bundling mortgage approval directly into that developer’s off-plan sales process. Pairing with Ellington extends the same model to a second major Dubai developer, and signals a bank betting that pre-approved home financing in Dubai will keep pulling buyers toward developments where the paperwork is already half done.

Business Intelligence & News

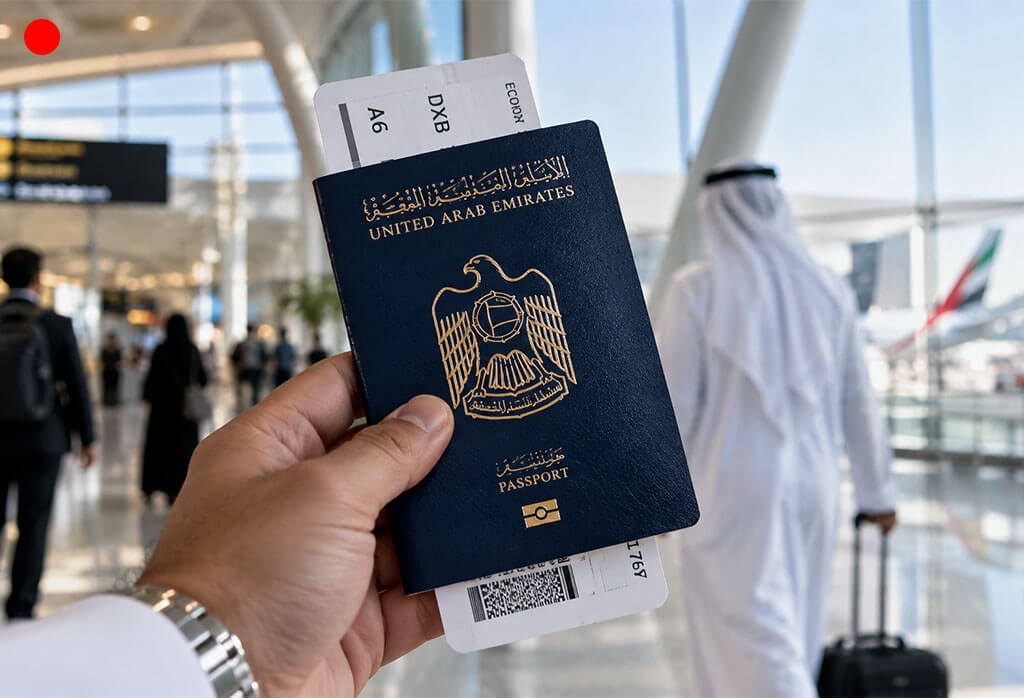
  • UAE passport ranks first globally in 2026, recording a Mobility Score of 182 and worldwide access of 91.9 percent, per Passport Reports’ September ranking.
  • The score covers 128 visa-free destinations, 44 visa-on-arrival or simplified-entry destinations, and 10 reachable through an eTA.
  • Europe, the Gulf, and the Middle East each show 100 percent overall access for UAE passport holders.
  • Only 16 destinations remain visa-required, and the UAE itself ranks 91st out of 199 for inbound travel.

How pre-approved home financing in Dubai works

Under the arrangement, ADCB and Ellington Properties Dubai buyers share a single digital application built for both off-plan and completed units. A dedicated relationship manager stays attached to the file from start to finish. Buyers are not shuffled between departments every time a payment milestone lands.

Off-plan purchases follow a specific structure. Eligible buyers can secure pre-approved financing covering up to 50% of a property’s value. That approval holds for 12 months and renews annually until the keys change hands. Dubai mortgage pre-approval usually means reapplying as construction milestones pass. This structure compresses that into one approval that carries a buyer through, year after year, until the building is complete. Construction timelines can stretch, and a tower meant to top out in 18 months sometimes takes 24. Annual renewal means a buyer’s financing plan does not lapse simply because a project runs long.

What the rates mean for buyers

Rate uncertainty is the usual complaint with early financing offers, since many are pegged to benchmarks that shift with the market. ADCB home loan rates on this program start at 3.49% per annum, fixed for three years. The bank is also waiving processing and valuation fees for a limited time, trimming the upfront cost of getting approved before construction even begins.

Three years of fixed pricing is a meaningful stretch in Dubai real estate financing. Buyers juggling handover payments alongside rent, or an existing mortgage, gain one less variable to plan around. A rate locked at signing does not move if the market tightens later.

A wider shift in Dubai property lending

Developers and banks across Dubai have leaned into bundled financing through 2026, pairing sales offices with in-house mortgage desks rather than leaving buyers to shop separately. The logic is consistent across these tie-ups. Get buyers pre-approved early, then keep them financed through a construction cycle that can run several years.

Ellington Properties, founded in Dubai in 2014, has built its reputation on design-led residential projects across Jumeirah Village Circle, Downtown Dubai and Palm Jumeirah. Linking that portfolio to ADCB’s mortgage arm gives the bank a direct channel into an active off-plan pipeline. It gives Ellington a financing partner its buyers can lean on instead of shopping the open market for a separate lender.

Pre-approved home financing in Dubai used to feel like a separate errand from choosing a unit. Off-plan property financing in Dubai buyers once treated as a background task, now sits inside the same conversation as picking a floor plan. For anyone weighing a reservation on an Ellington unit, the practical move is to ask about pre-approval before signing anything. A rate locked today, at 3.49% for three years, could look considerably better than whatever the market offers by the time a project reaches handover.

Share this post

on your favourite social platforms

or copy the link